
Yes, Rocket Mortgage can finance a modular home, but only once the home is finished, set on a permanent foundation and classified as real property. Rocket Mortgage does not offer construction loans, so if you are building a new modular home, you will usually need a separate construction loan first and can then refinance into a Rocket Mortgage loan after the home is complete. Buying a modular home that is already built works much like buying a site-built house.
Because modular homes are built to the same state and local codes as site-built houses, lenders that follow Fannie Mae guidelines treat a qualifying modular home like any other house.
How Rocket Mortgage Treats Modular Homes
Rocket Mortgage’s own guidance on modular homes separates two situations: buying a finished home and building a new one.
| Situation | Can Rocket Mortgage finance it? | What you need |
| Buying an existing modular home | Yes | The home must be on a permanent foundation and titled as real property, like a site-built house |
| Building a new modular home | Not the construction phase | A construction loan, and possibly a land loan, from another lender |
| Refinancing after construction | Yes | The finished home can be refinanced into a permanent mortgage |
For a new build, the real question is timing. A half-finished home can’t secure a standard mortgage, so the mortgage starts once the home is installed, inspected and complete.
Modular vs. Manufactured: Why the Difference Matters
Lenders treat modular and manufactured homes differently.
- Modular homes: built in sections in a factory to the state or local building code, then set on a permanent foundation. Fannie Mae states that modular, prefabricated, panelized and sectional homes are not manufactured housing and receive the same consideration as site-built properties.
- Manufactured homes: built on a permanent chassis to the federal HUD code, which has applied since June 1976. Rocket Mortgage began offering a conventional loan for manufactured homes in 2022, but the home must be on a permanent foundation and titled together with the land.
Rocket Mortgage does not finance manufactured or mobile homes built before June 15, 1976. Homes that are not attached to a permanent foundation are usually treated as personal property and financed with a chattel loan, which is a different product with shorter terms and typically higher rates.

Financing a New Modular Home Step by Step
Because Rocket Mortgage does not fund construction, a new modular project usually moves through two stages of financing.
Stage 1: Construction Financing
A construction loan from a bank, credit union or specialty lender pays for the home, the foundation and site work as the project progresses. Funds are typically released in stages, called draws, as work reaches agreed milestones. Some lenders also offer a construction-to-permanent loan that converts into a mortgage automatically, which avoids a second closing.
Stage 2: The Permanent Mortgage
Once the home is finished, the construction loan is paid off with a permanent mortgage. That’s the point where Rocket Mortgage can step in. The appraiser will value the home against comparable sales in the area, and Fannie Mae allows appraisers to use site-built homes as comparables for modular homes, with adjustments where construction methods differ.
Stage 3: Closing and Move-In
After the refinance closes, you make regular mortgage payments on the finished home and land. If you already own the land, its value can count toward your equity in the project.
What a Modular Home Costs at Azure Printed Homes
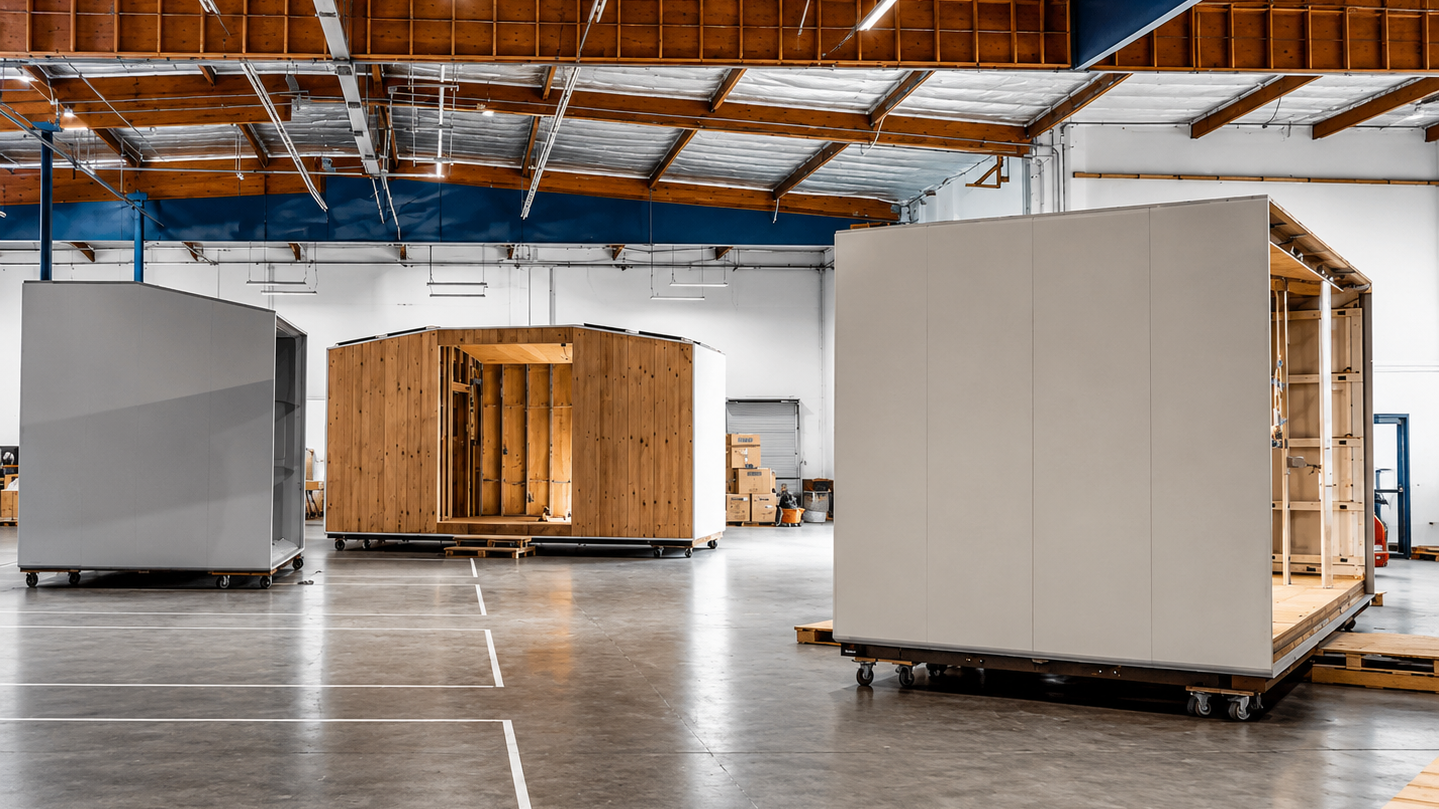
At Azure Printed Homes, our permanent Homes & ADUs are built in our factory in Gardena, California, and set on a foundation on your property. A fixed model price gives your lender a firm number for the biggest line in the construction budget.
| Model | Dimensions | Layout | Starting price |
| A-360 | 18 x 20 ft | 1 bedroom, 1 bath, kitchen | $89,900 |
| A-540 | 18 x 30 ft | 1 bedroom, 1 bath, kitchen | $134,900 |
| A-720 | 18 x 40 ft | 1 or 2 bedrooms, 1 bath, kitchen | $174,900 |
| A-900 | 18 x 50 ft | 2 bedrooms, 1.5 baths, kitchen | $219,900 |
Our prices include factory-completed electrical, mechanical and plumbing work and standard finishes. Site and foundation work, permit fees and delivery are separate, and delivery for homes costs about $5 per mile. Heating and cooling are an additional cost. For larger or more complex projects, our custom homes are priced at approximately $400 per square foot.
We also offer financing through our partner, Acorn Finance, and you can reserve a model with a fully refundable $250 deposit. For a permanent home, many buyers combine a construction loan with a mortgage.
What About Homes on Wheels?
Our Homes on Wheels are a different product. The X-180, X-270 and X-360 are built on an included chassis and certified at the factory as park models. A park model on wheels is not a modular home on a permanent foundation, so it does not qualify for a standard mortgage in the same way. Buyers usually look at personal loans or other financing options for these units, including the financing available through Acorn Finance.
How Long a Modular Project Takes
The timeline affects how long you carry a construction loan before converting to a mortgage. For our ADUs and homes, a site plan typically takes two to four weeks, local approval can take 8 to 24 weeks, fabrication takes four to six weeks, and delivery and installation about one week. Because the home is built in our factory while your site is prepared, an ADU or home can be delivered within 90 to 120 days where approval is quick.
For permanent homes, we handle the building permit for the factory-built unit, while the owner handles permits for the foundation, grading, drainage and utilities. Lenders usually won’t release construction funds until these approvals are in place, so start on permits early.
Questions to Ask Your Lender
- Construction financing: do you offer construction loans or construction-to-permanent loans for modular homes?
- Draw schedule: how are payments to the manufacturer handled while the home is built in the factory?
- Appraisal: how will the appraiser value a modular home in my area, and which comparable sales will be used?
- Foundation: what foundation and title requirements does the home need to meet?
- Refinancing: what is required to convert the construction loan into a permanent mortgage once the home is complete?
Planning a Modular Project With Azure Printed Homes
Before approving construction financing, a lender will ask for plans, a budget and a schedule. At Azure Printed Homes, every project follows the same sequence:
- Client and site assessment: we review your goals and your property to determine what can be built there.
- Design and engineering: our team prepares architectural, structural, MEP and energy plans for the model and the site.
- Approvals: we handle the building permit for the factory-built unit, while the owner handles permits for the foundation, grading, drainage and utilities.
- Fabrication: the home is built in our factory while the site is prepared, which shortens the overall schedule.
- Delivery and installation: the finished home is shipped by truck and installed on the foundation, usually in about a week.
Each step produces documents a lender typically asks for, including the plans, the permit, the fixed price of the unit and the project schedule. Sharing them early helps the lender set a draw schedule that matches the payment milestones for the home.
Why Build Quality Matters to an Appraiser
When a modular home is appraised for a permanent mortgage, its construction quality and durability affect how it compares with nearby homes. Here is how our homes are built:
- Structure: the structural shell of every home is printed by robots with consistent precision, then finished in our factory.
- Weather performance: our structures are watertight, highly insulated and pest resistant, and designed for wind speeds of up to 150 mph and for snow loads under the ASCE 7-10 standard.
- Materials: we print with a material that is more than 60% recycled plastic, or build with light-gauge steel for larger homes and for projects in high fire hazard severity zones.
- Warranty: our ADUs and homes carry a ten-year warranty against defects in materials and workmanship.
In California, our units are designed to comply with Title 24 energy standards, which is one more item an appraiser or lender may ask about. Keep the plans, labels and warranty documents in one place, because the appraiser and the lender will ask for them again at refinance.
Conclusion
Rocket Mortgage can finance a modular home once it is finished, on a permanent foundation and titled as real property. It does not fund the construction phase, so a new modular build usually starts with a construction loan from another lender and ends with a permanent mortgage, which Rocket Mortgage can provide. Existing modular homes are financed much like site-built houses.
Our Homes & ADUs start at $89,900 for the one-bedroom A-360 and go up to $219,900 for the two-bedroom A-900, which gives you a clear starting point for a construction budget. Contact us to talk through your project and the financing options available.